9655 Angel Oak Drive
Principal and interest only. Property taxes and insurance are not included, so the actual payment will be greater. About $21,300 down (8.0% of the price) covers the seller's equity, and 314 monthly payments of $1,465.04 remain, the last due January 2053. Estimated from the seller-reported loan terms and the public purchase record. The loan servicer must approve the buyer and sets the final figures. See how the numbers work.
I am a Realtor, not a loan officer. Check with your lender to verify these numbers and rates.
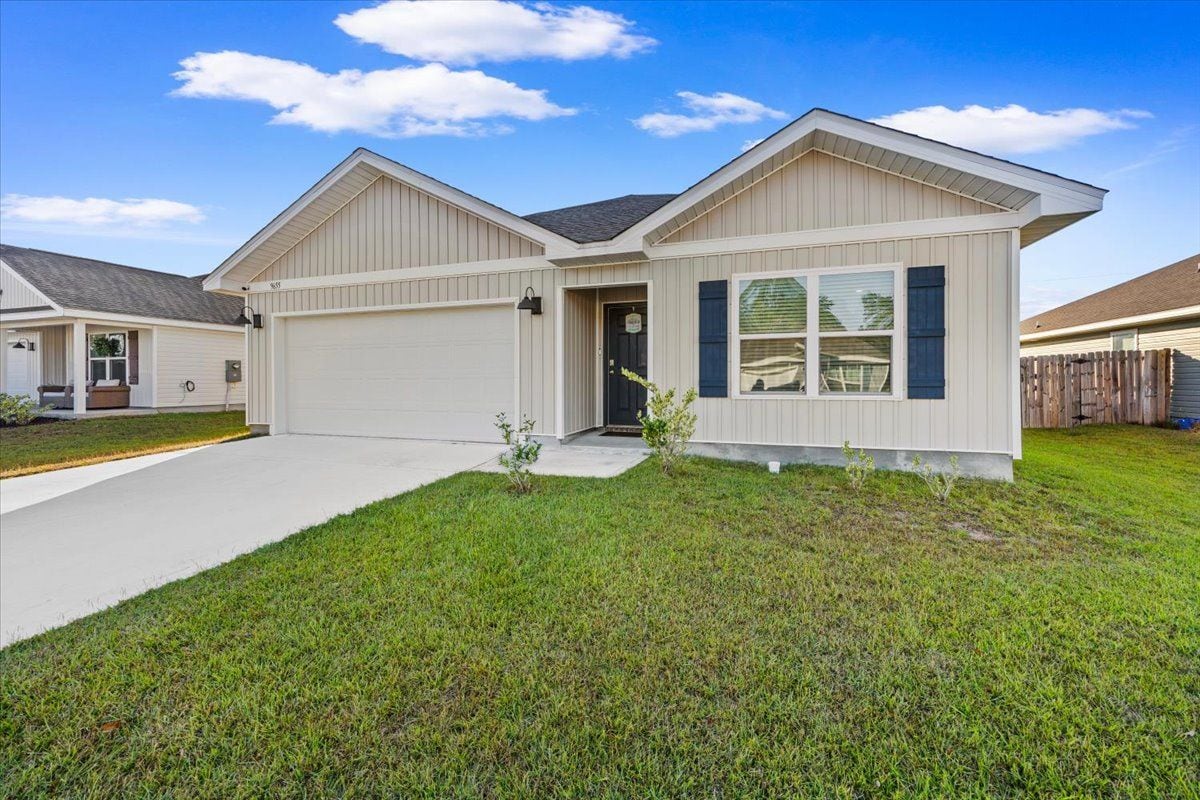
Built in 2022, this single-story home in northwest Pensacola's Glenhollow neighborhood has three bedrooms, two full baths and an open kitchen, dining and living area, with a fenced backyard and an attached garage. The seller's VA loan can pass to a qualified buyer at its original rate, so the payment comes from a 2022 loan and not from today's market.
Take over the loan, keep the rate
The home's VA loan dates from its first sale in December 2022. A qualified buyer can take it over as it stands: the same fixed rate, the same payment and the years already paid down. Here is how that compares with a new 30-year VA loan for the same amount at 7.5%.
Carried to the end of each loan, the assumed loan costs about $153,000 less in principal and interest and is paid off 3.8 years sooner. It also pays down faster: after five years you would owe about $10,900 less than on the new loan.
- Loan
- VA loan, 5.5% fixed (5.58% APR)
- Remaining balance
- About $243,600 after the November 2026 payment
- Cash for the seller's equity
- About $21,300, the price less the balance (8.0%)
- Payments left
- 314 monthly payments, about 26.2 years
- Who can assume it
- Any buyer the loan servicer approves. VA does not require the buyer to be a veteran; ask me whether the seller needs a VA-eligible buyer who can substitute entitlement.
- Approval
- The servicer reviews the buyer's credit and income. VA gives a servicer with automatic authority 45 days to decide once the application is complete.
What you skip by assuming
A new VA loan carries charges that an assumption does not. For the same loan amount and the same cash down, here is the difference at the closing table.
| Loan cost | New VA loan | Assume this loan |
|---|---|---|
| VA funding fee | 1.5% · $3,654 | 0.5% · $1,218 |
| Lender or servicer fee | Up to 1% · $2,436 | Up to $704 |
| VA appraisal | $700 | Not charged |
| Florida intangible tax on a new mortgage | $487 | None |
| Total | Up to $7,277 | About $1,922 |
less in loan costs at closing. The low figure assumes a lender that charges no origination fee, the high figure one that charges the full 1% VA allows.
- If you are exempt from the funding fee (for example, you receive VA disability compensation), you pay it on neither loan, and the difference is about $500 to $2,900.
- With little or nothing down, the funding fee on a new VA loan is higher than shown here: 2.15% on first use and 3.3% after first use, against 0.5% on an assumption. The 1.5% above reflects the cash this assumption already requires.
- Paid in cash: the assumption funding fee and the servicer's fees are due at closing and cannot be added to the loan. The servicer's fee is VA's $300 processing cap plus its $404 allowance for this region.
- The same either way: Florida documentary stamp tax, title insurance, recording, homeowners insurance and tax reserves are not in this comparison.
This is a comparison of published rules and fee schedules, not a loan estimate. I am a Realtor, not a loan officer. Check with your lender to verify these numbers and rates. Sources: VA funding fee chart (effective April 7, 2023); VA Circular 26-23-10 and its Change 1; VA Circular 26-24-5; VA appraisal fee table (effective May 1, 2026); 38 CFR 36.4313; sections 199.133 and 199.145, Florida Statutes. Checked November 17, 2026.
One level, built in 2022
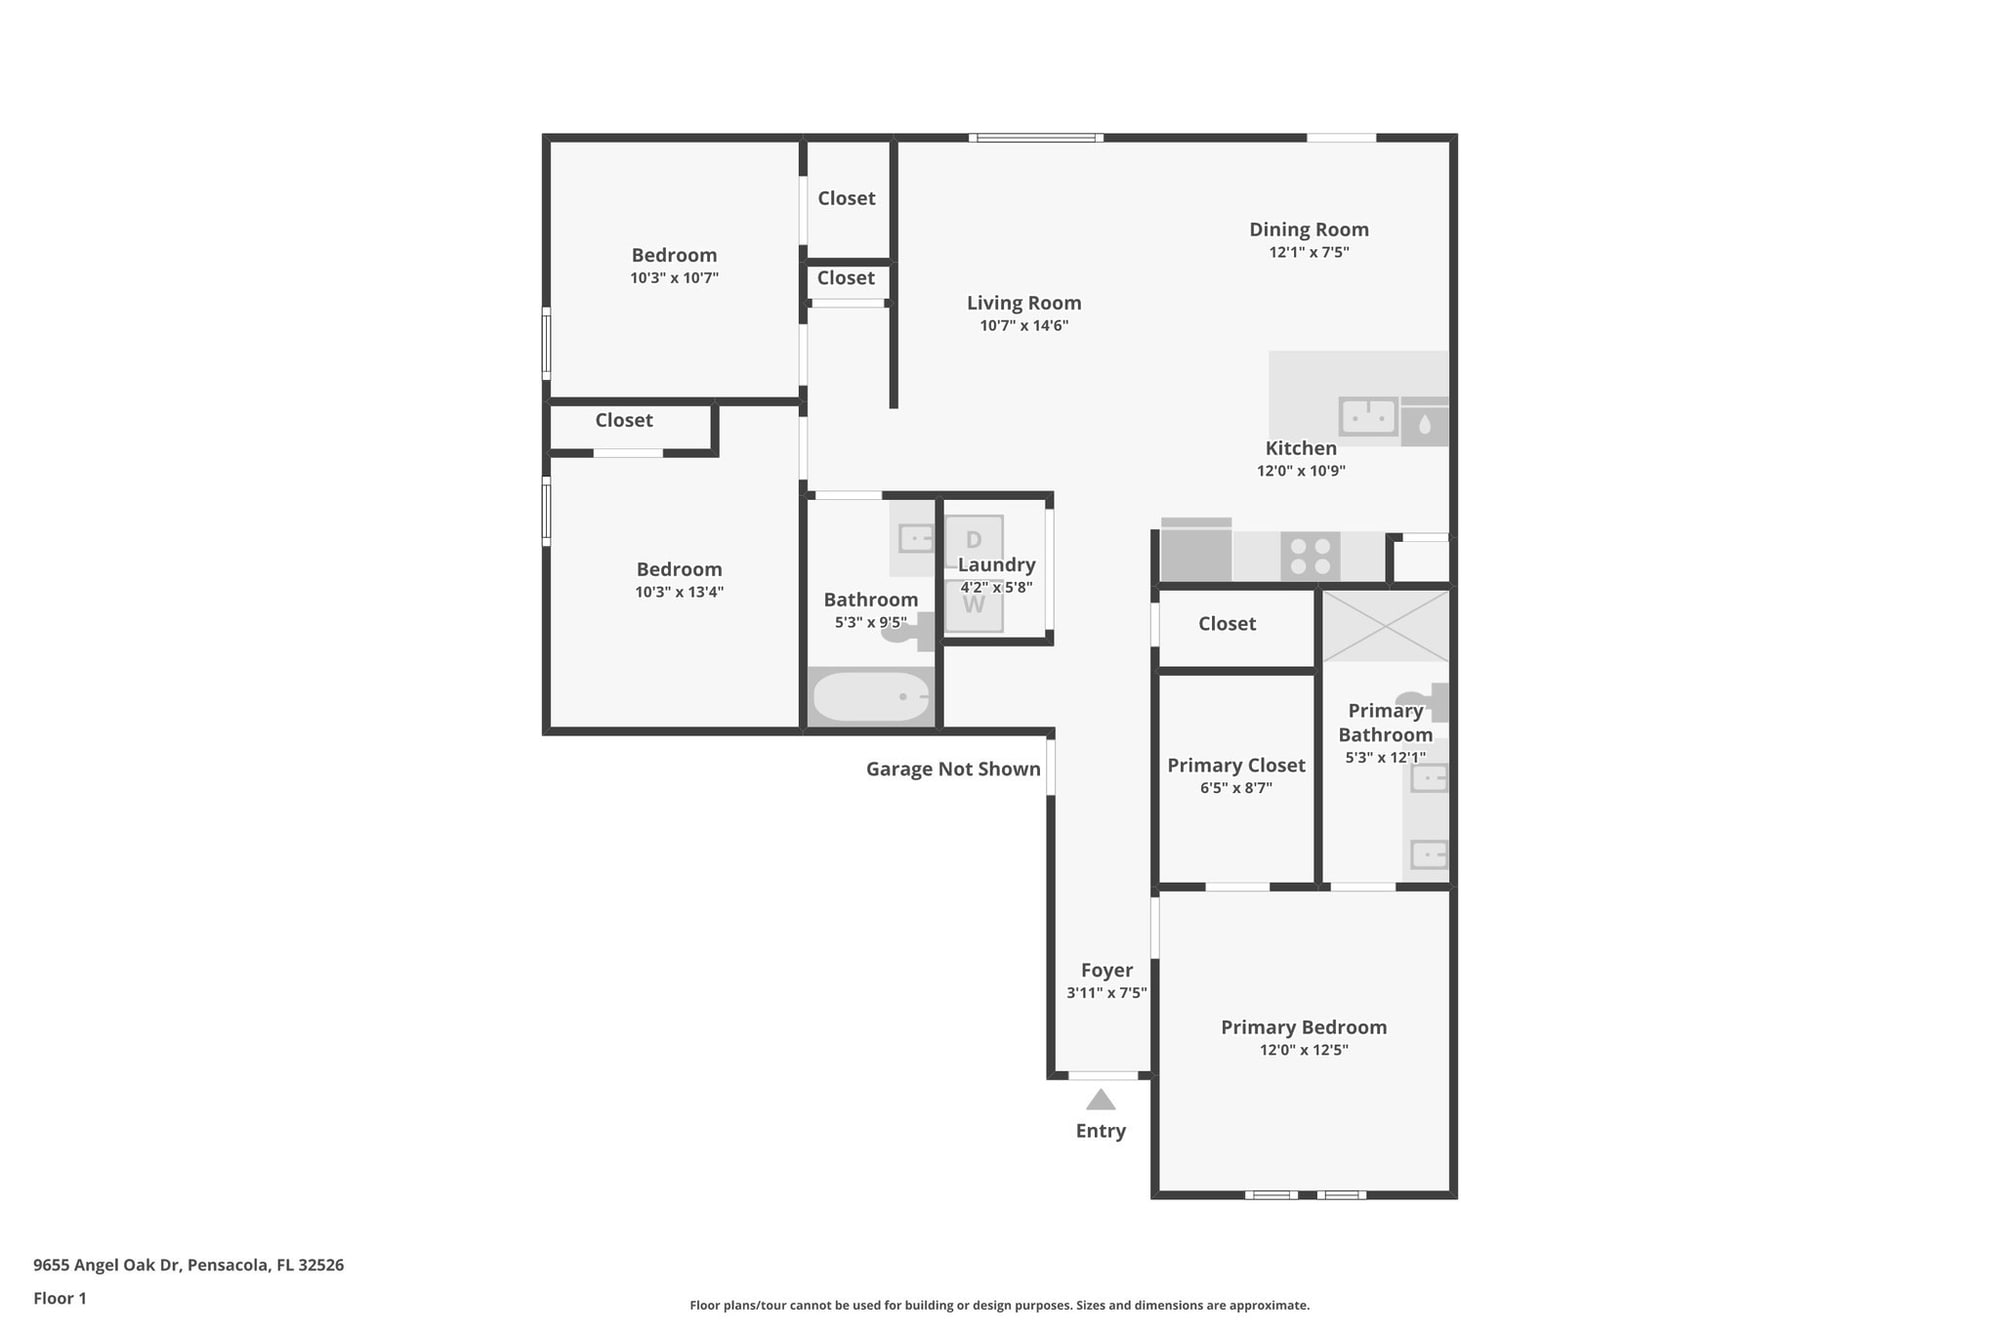
County records show 1,270 square feet of living area on a lot of about 0.16 acre. The floor plan sets the primary suite at the front of the home and the other two bedrooms off their own hall, with the kitchen, dining area and living room open to one another at the back.
Inside 9655 Angel Oak
Twenty-four photographs of the home, the yard and the street. Select any photo to open the full gallery.
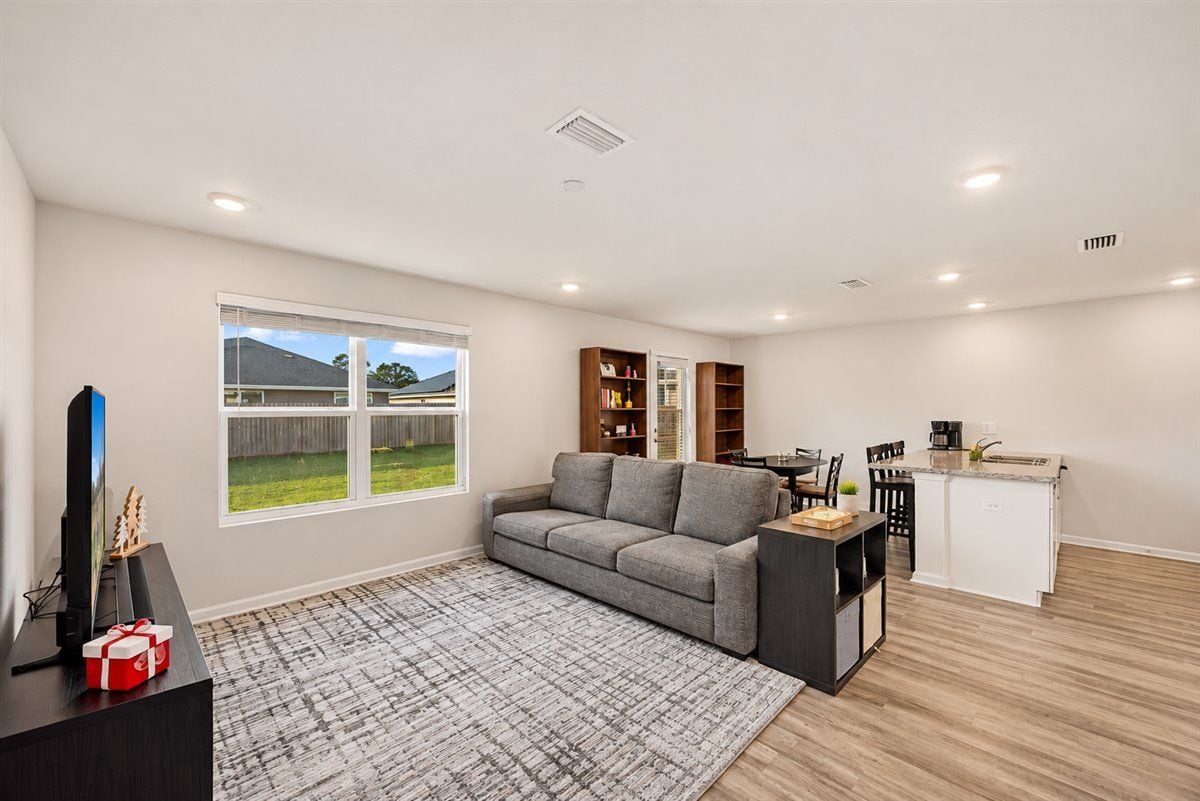
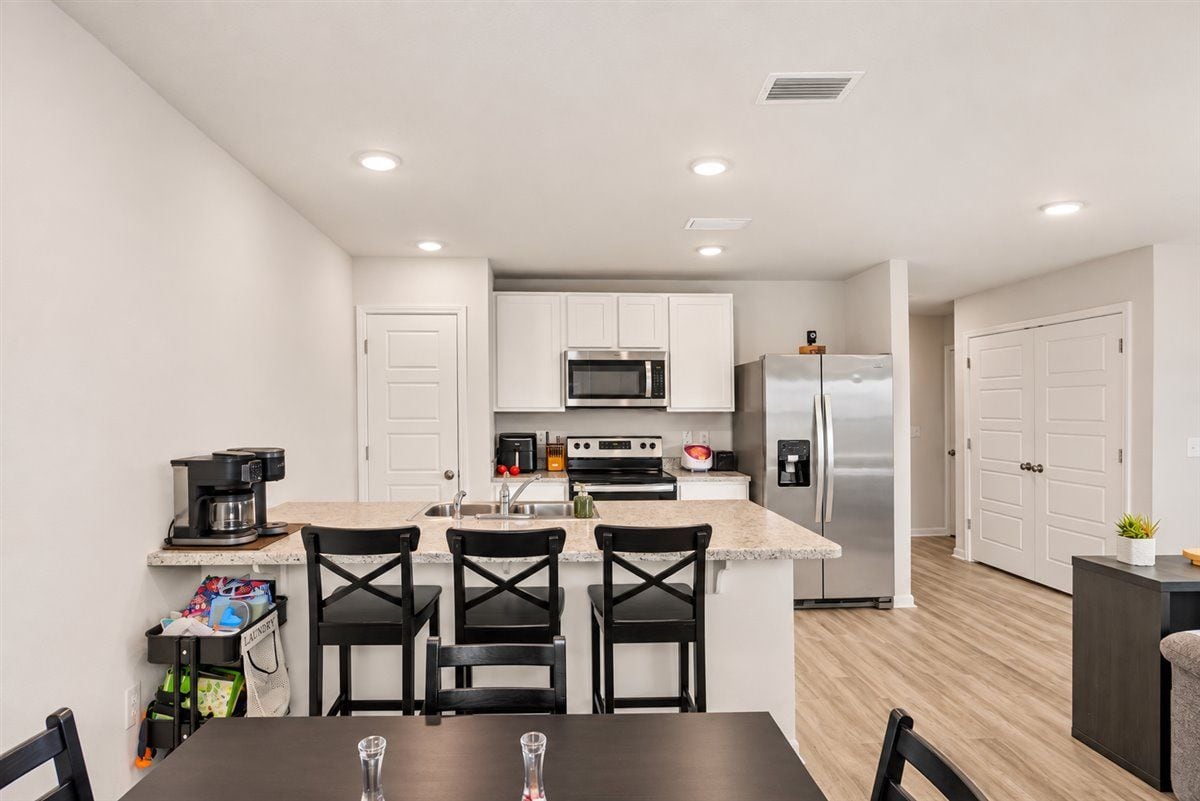
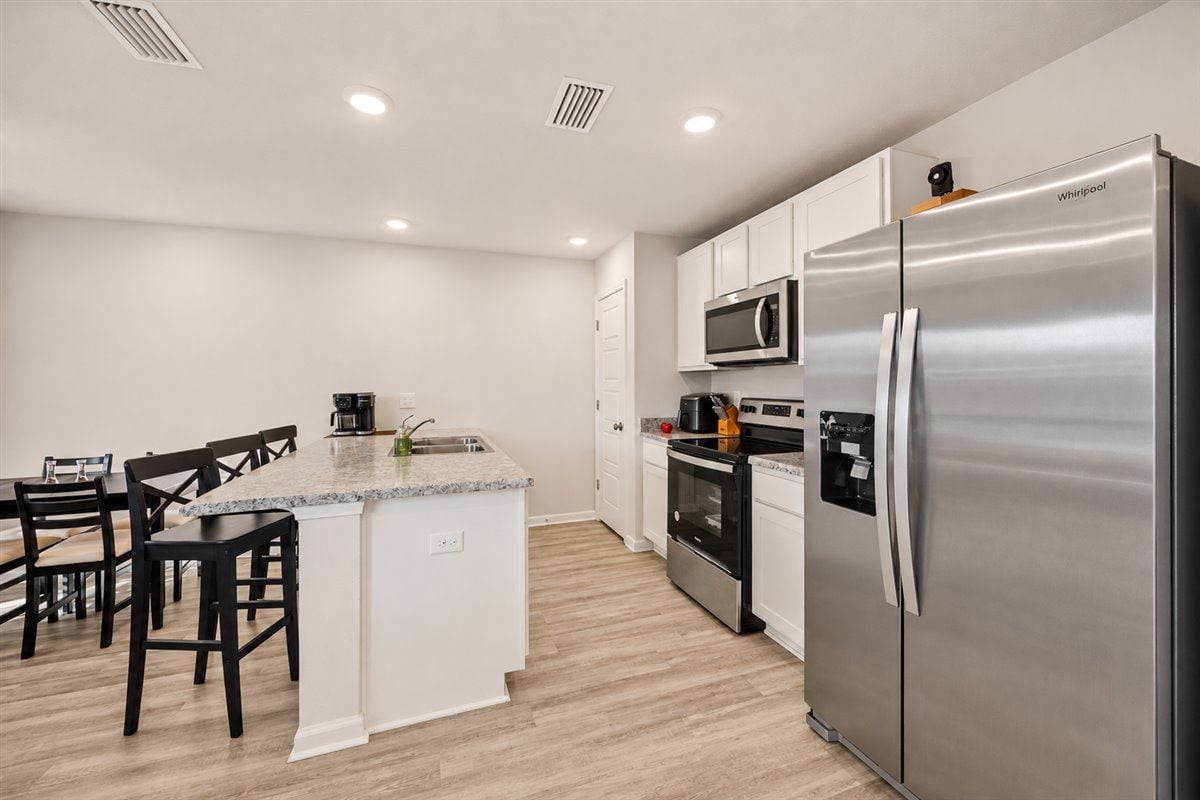
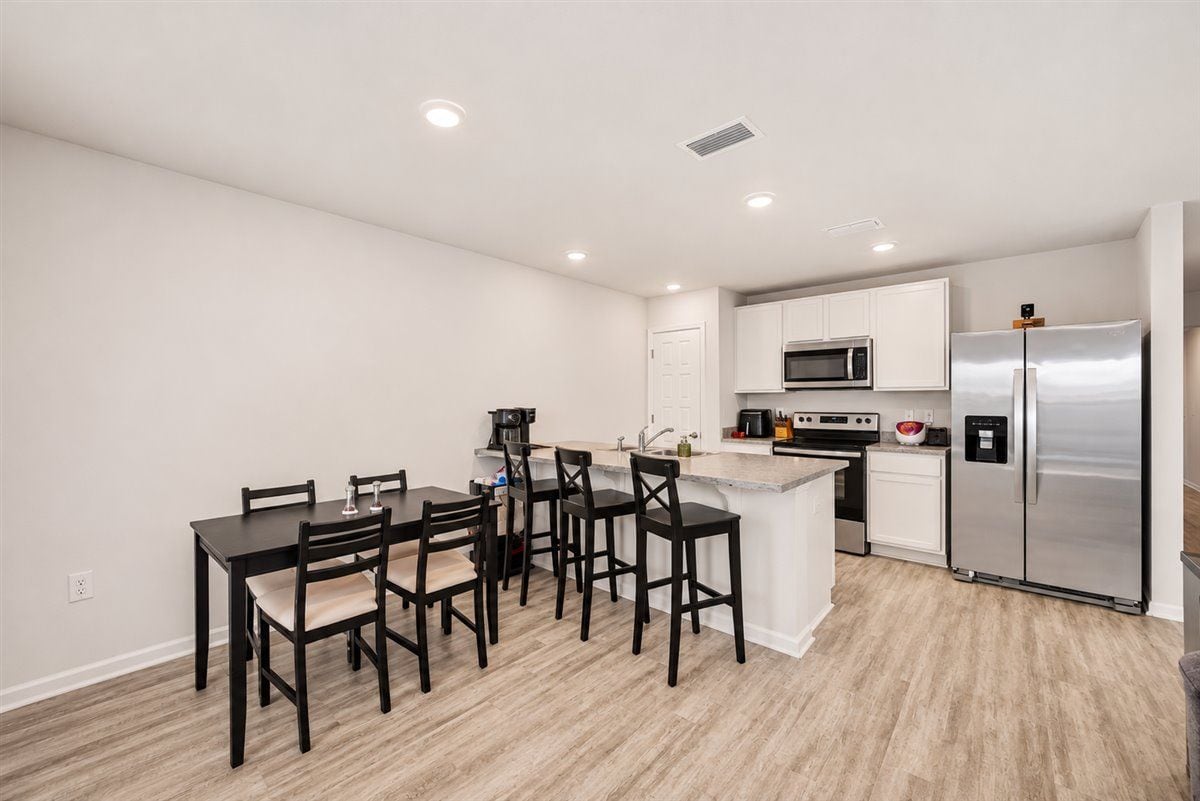
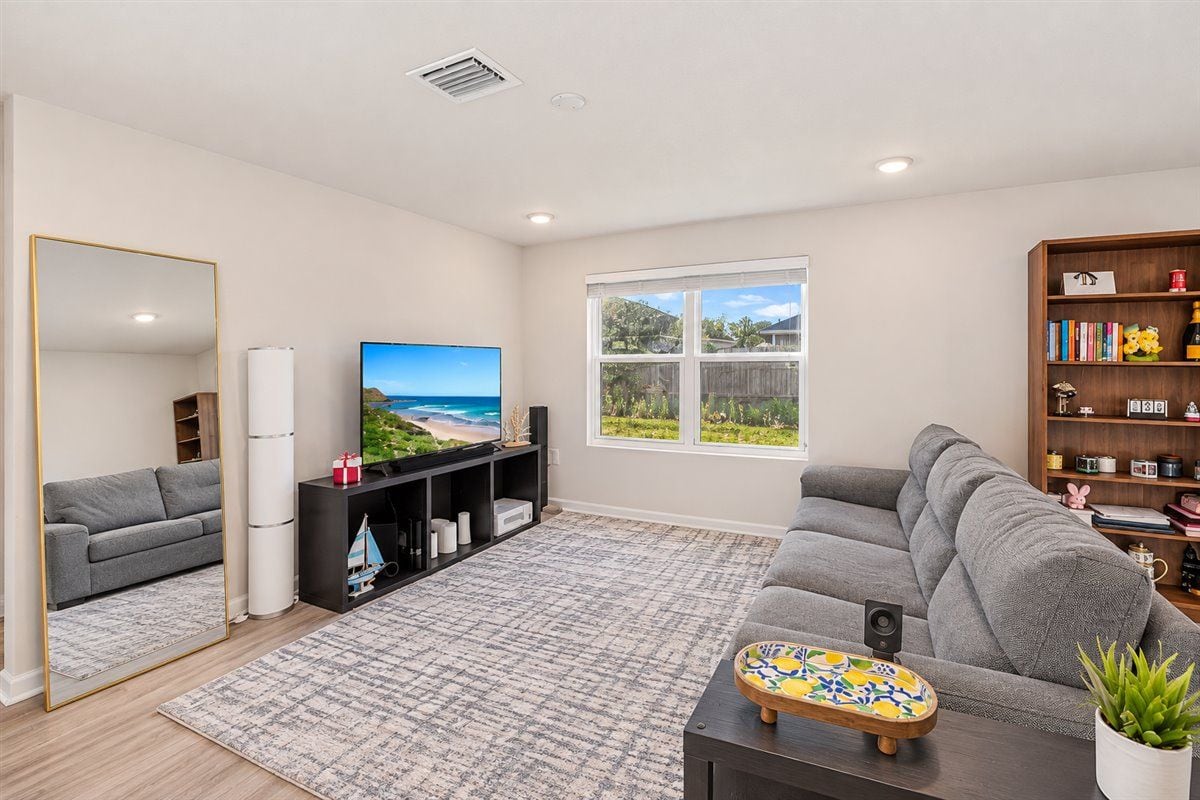
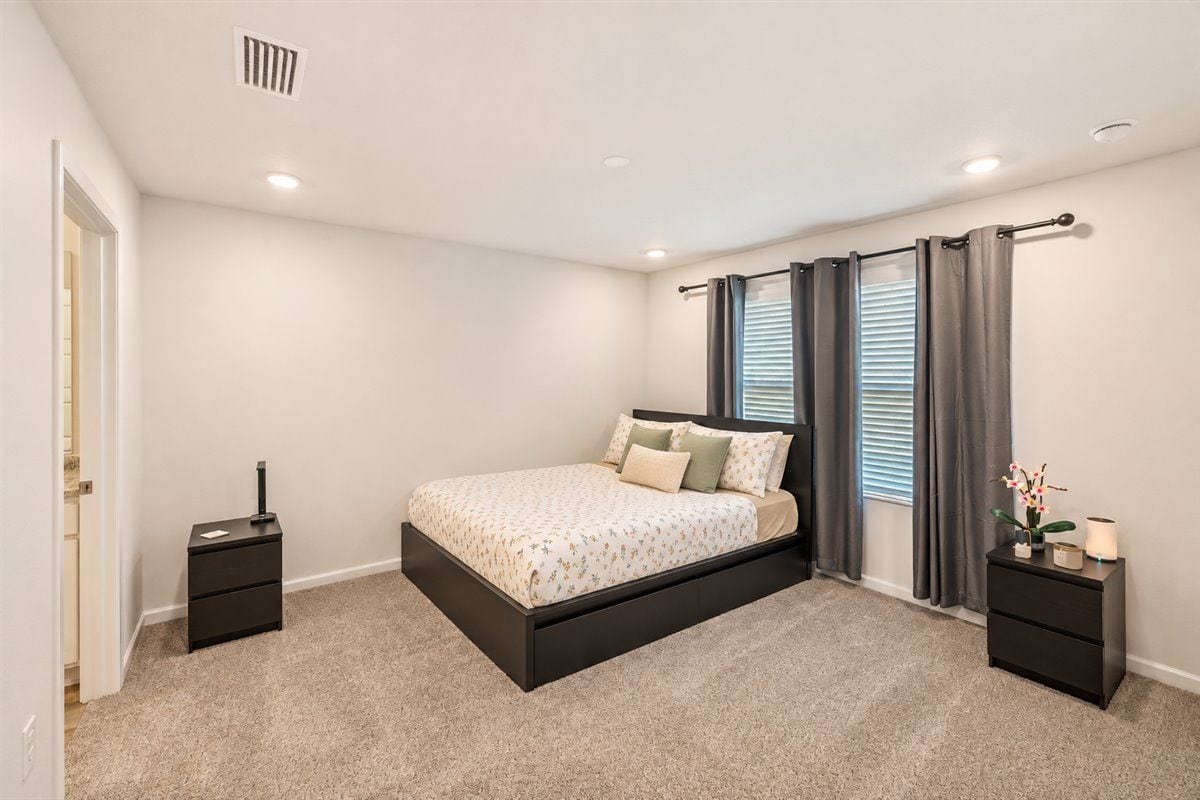
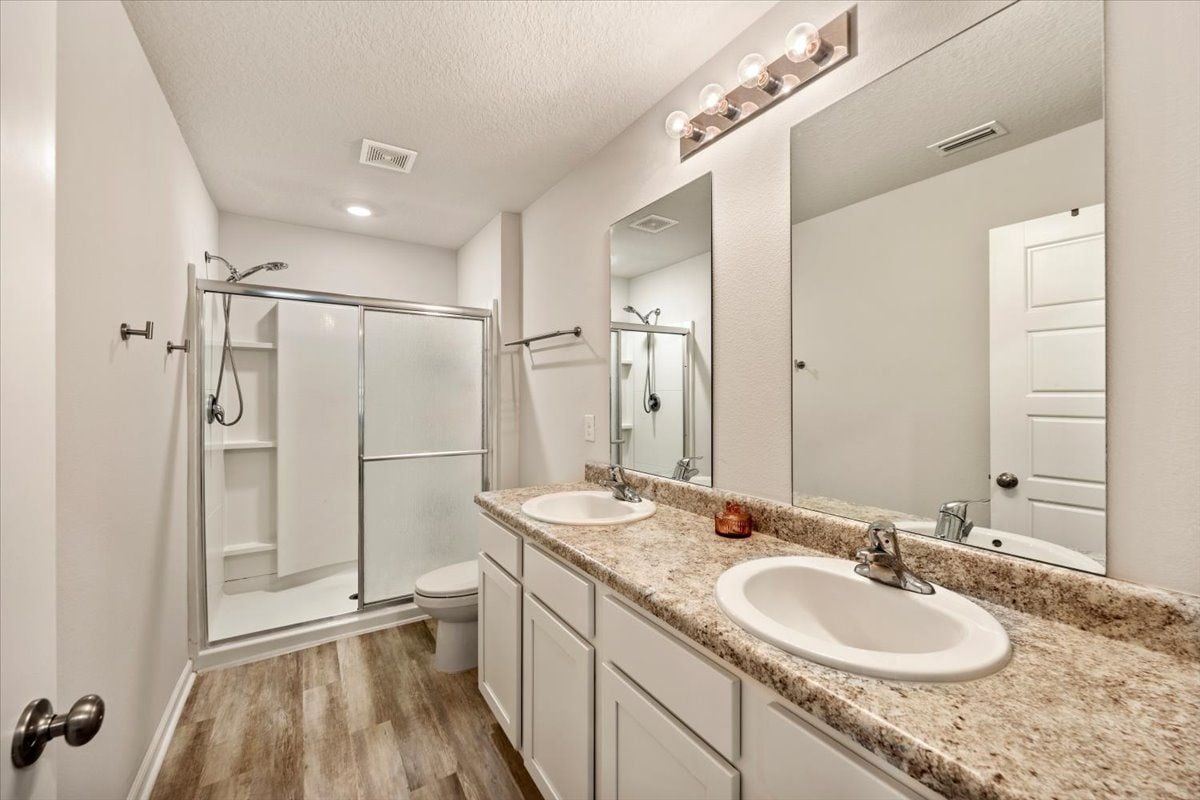
See all 24 photos
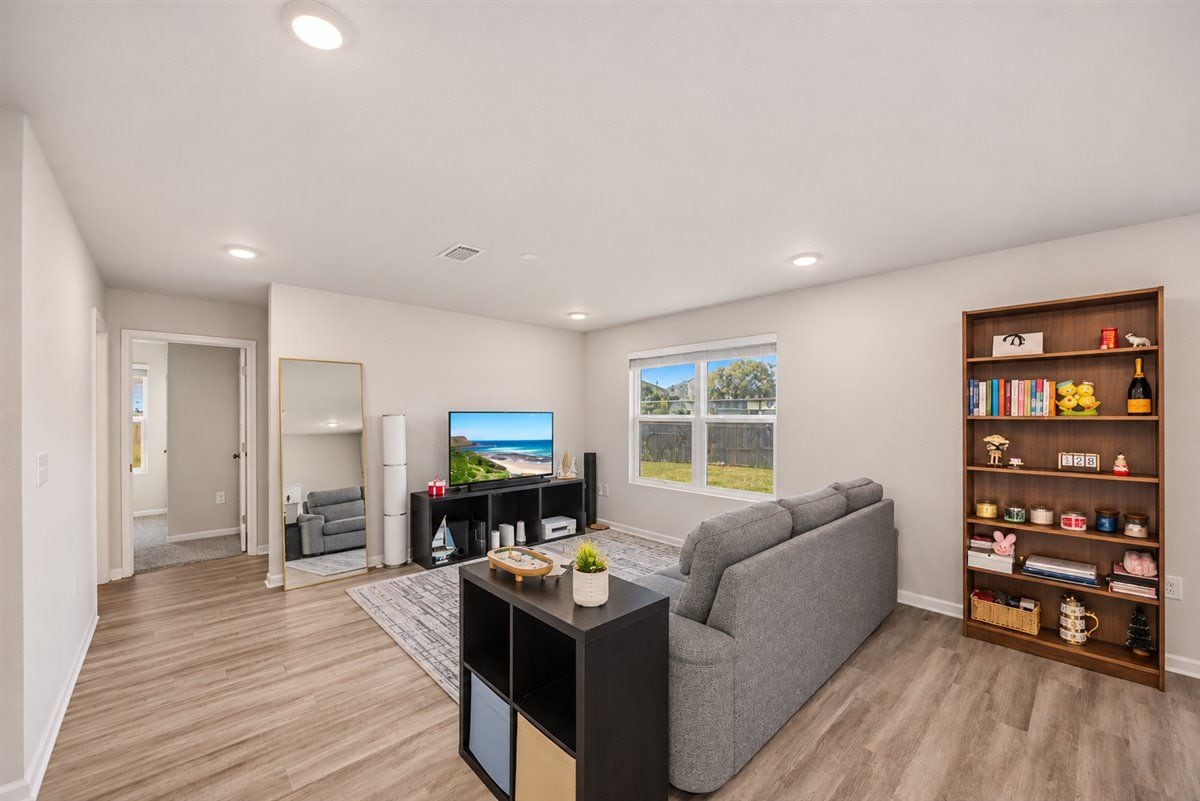
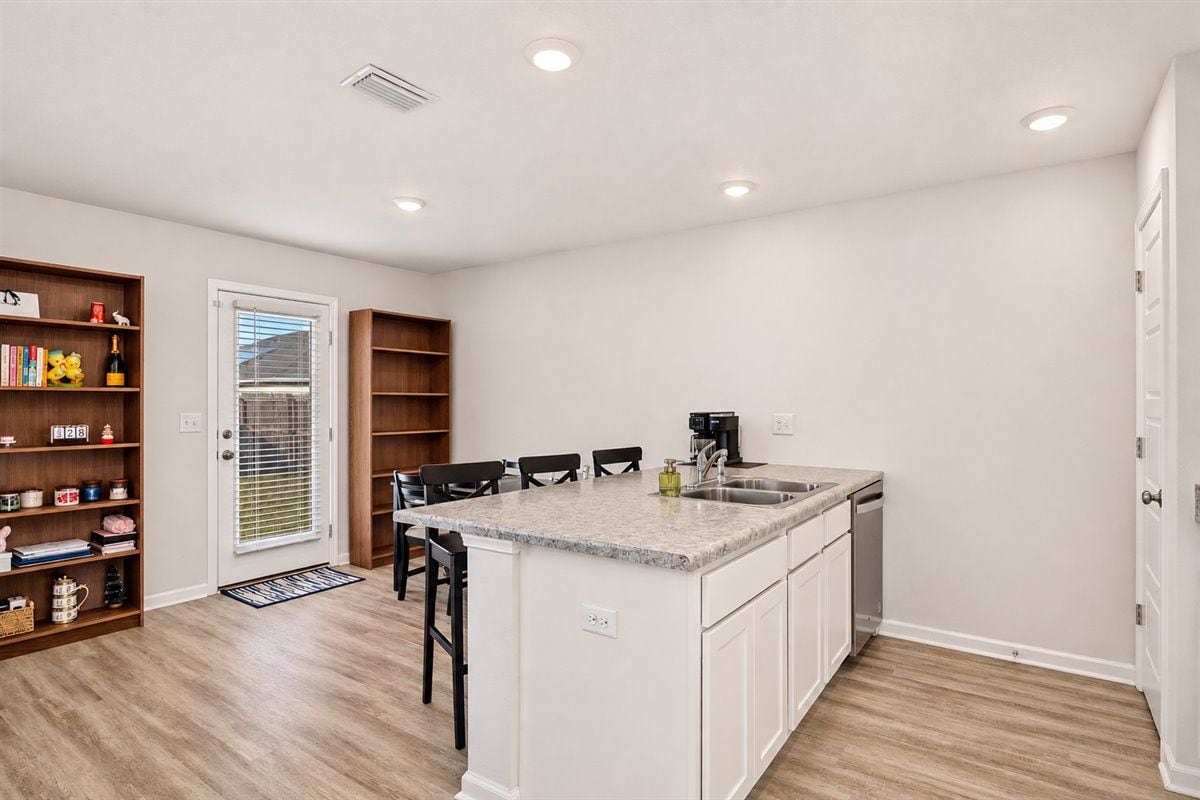
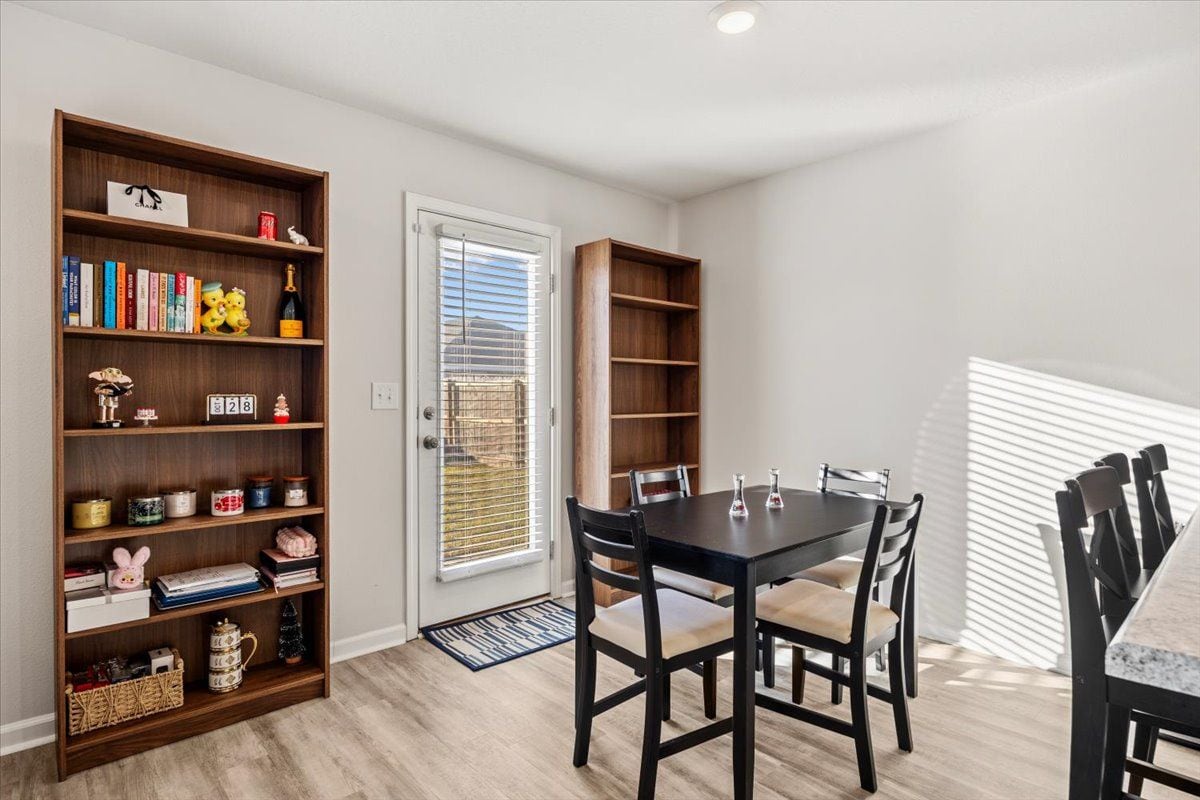
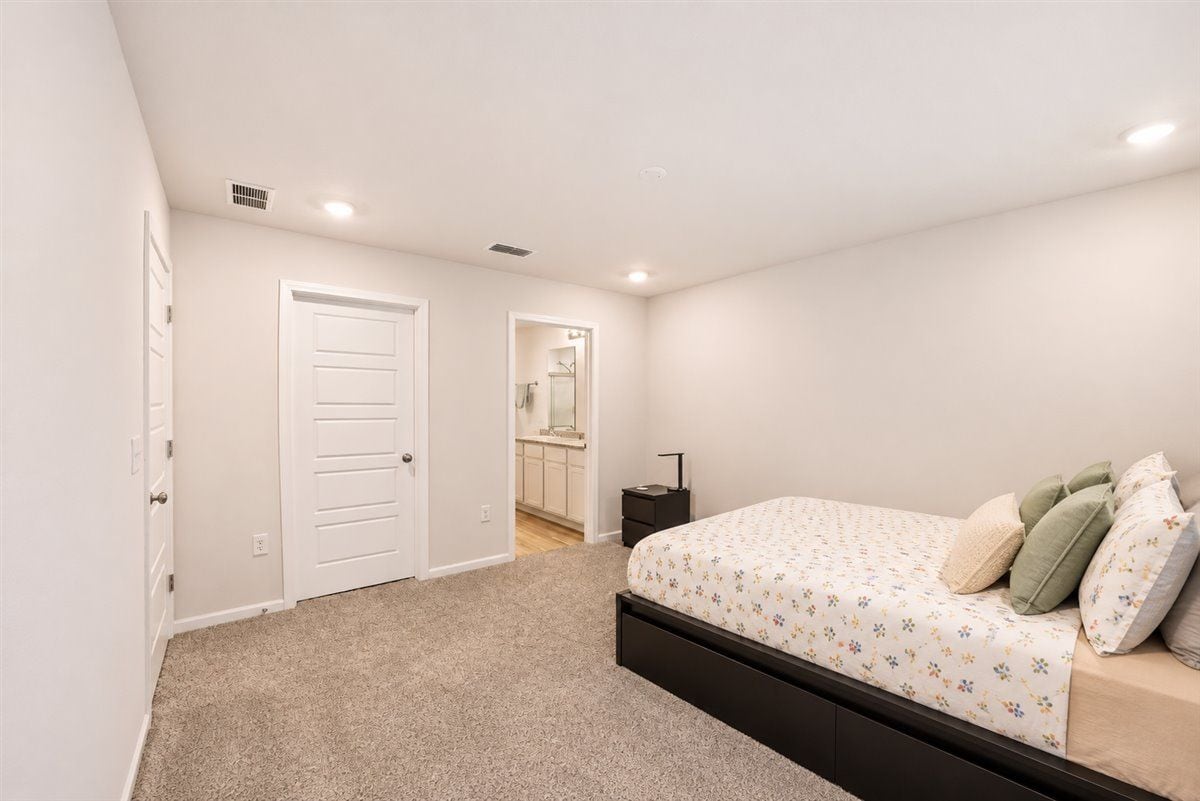
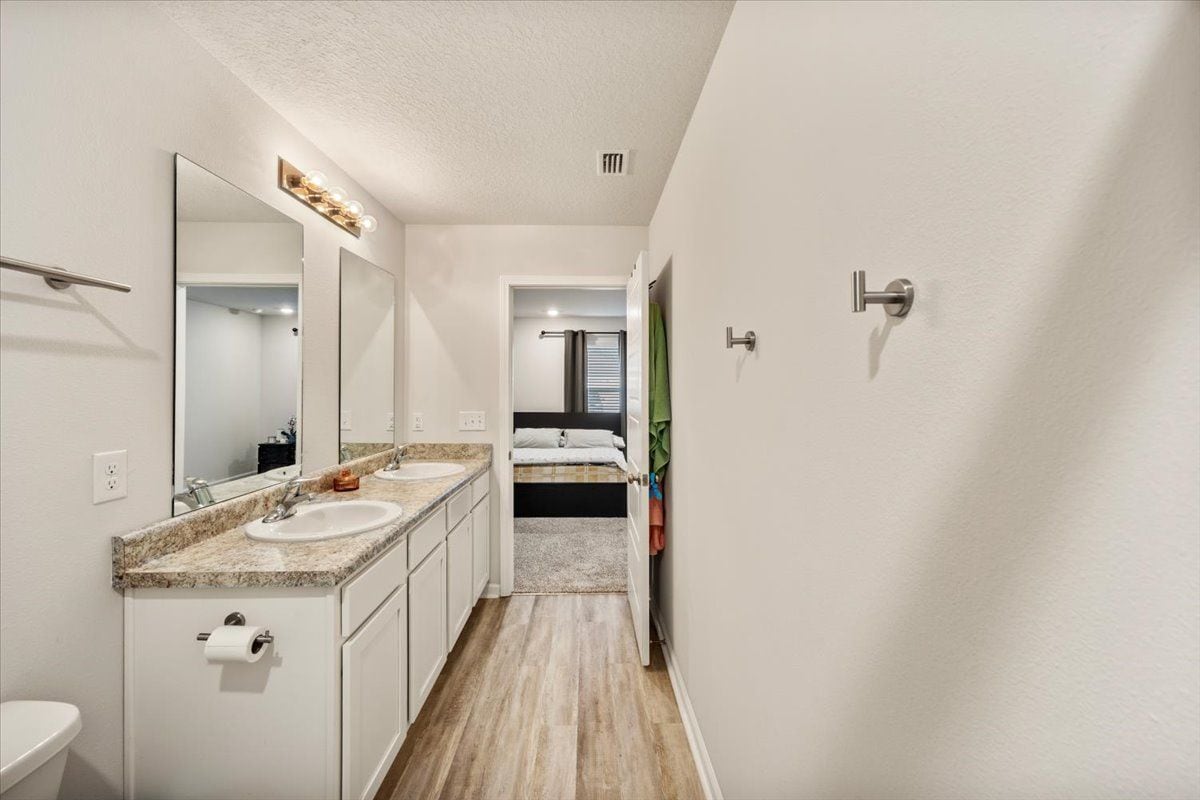
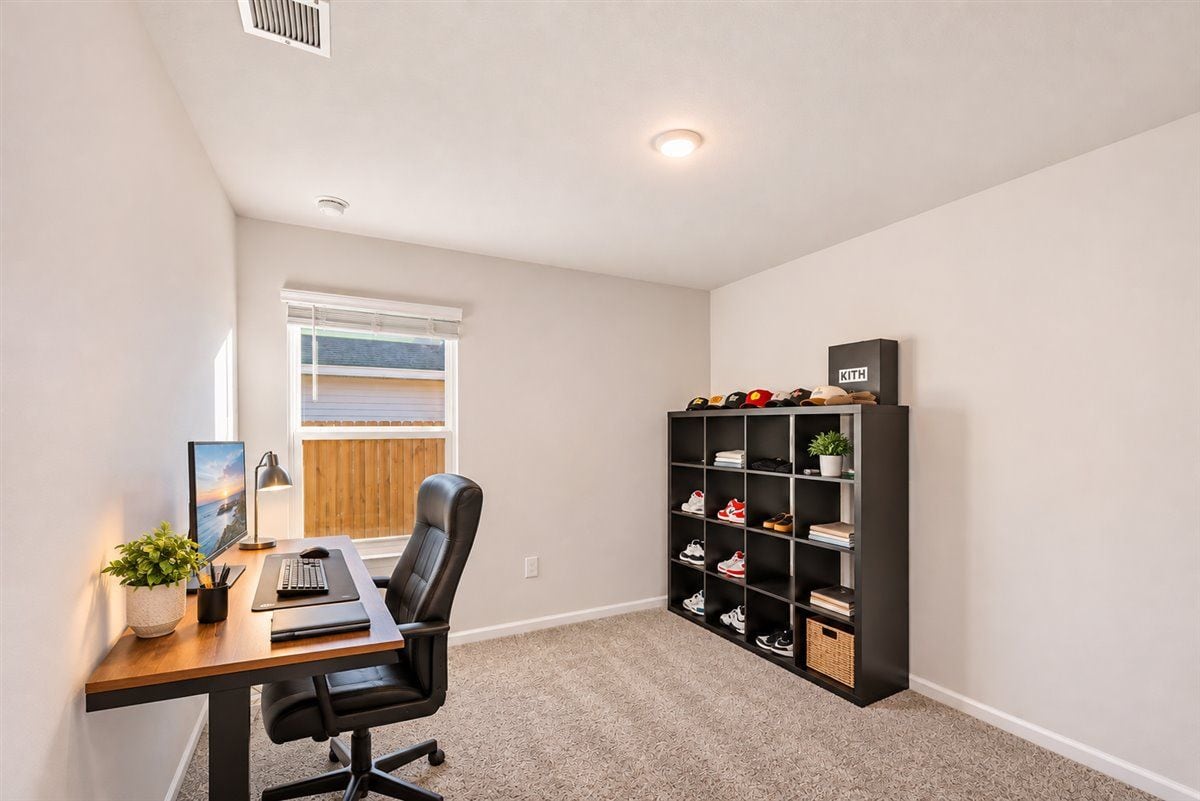
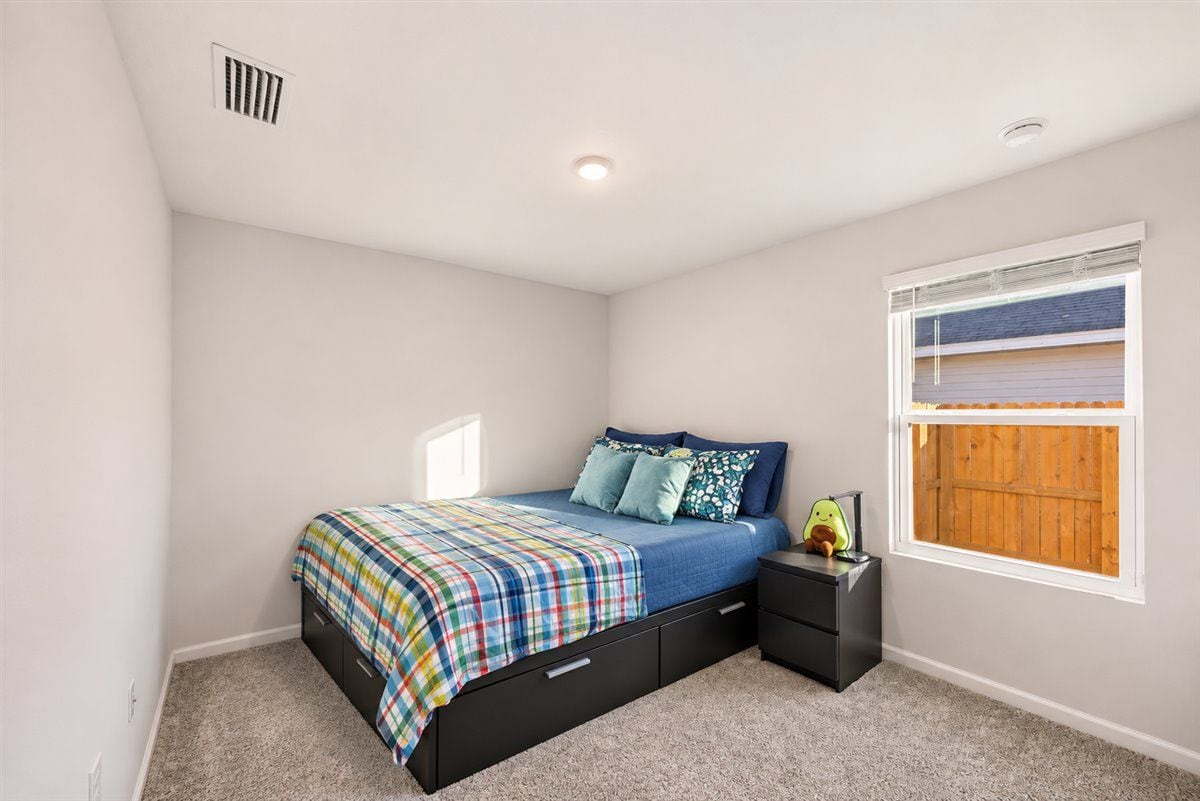
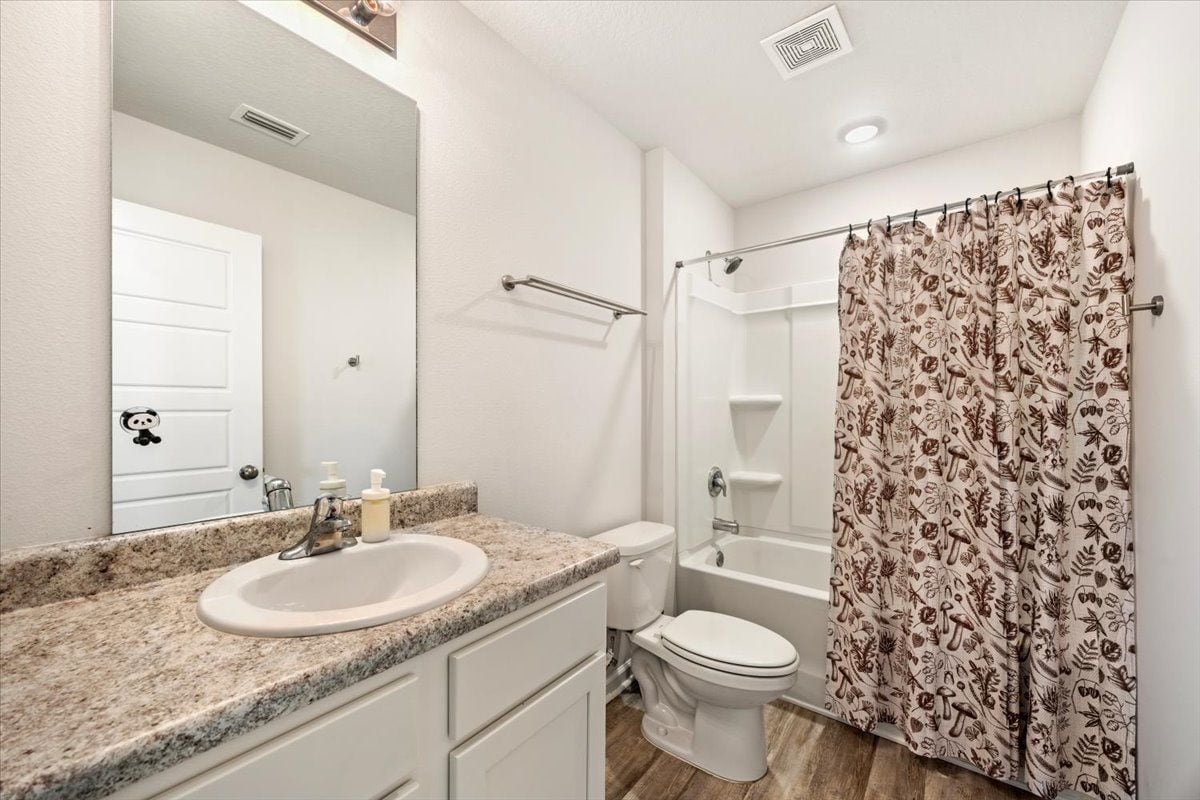
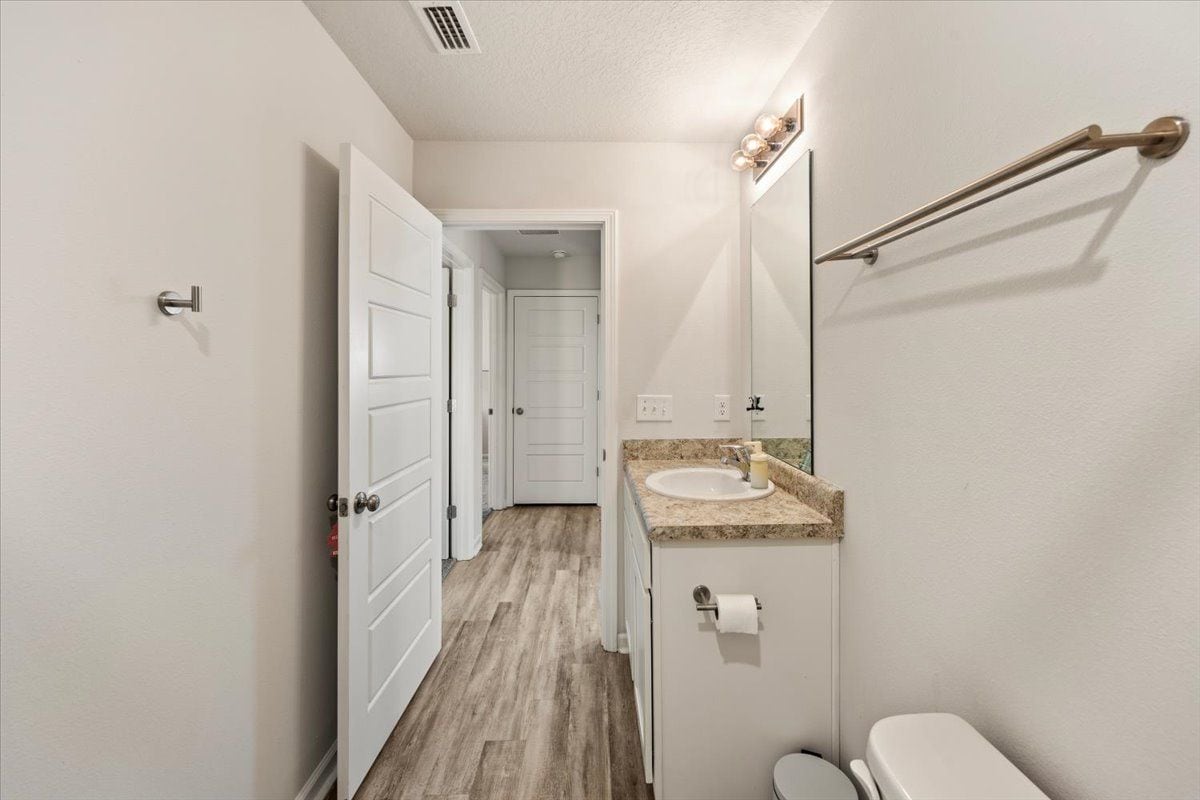
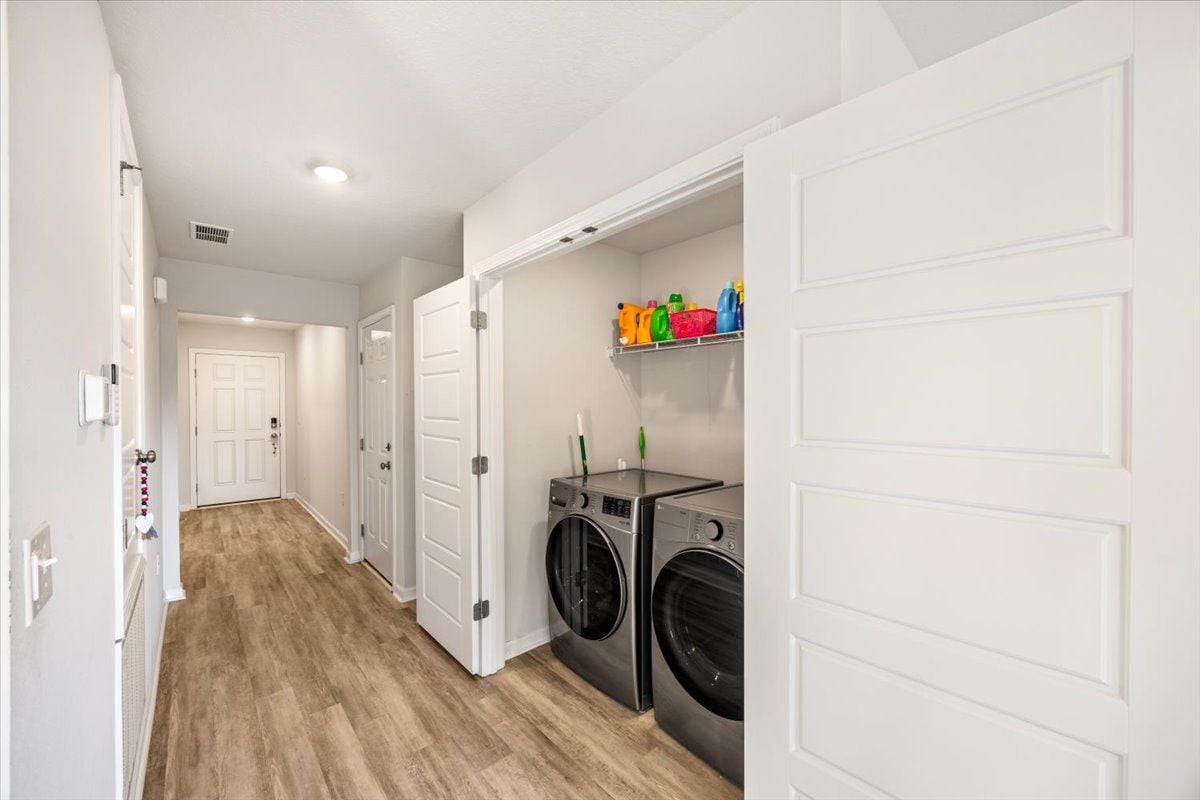
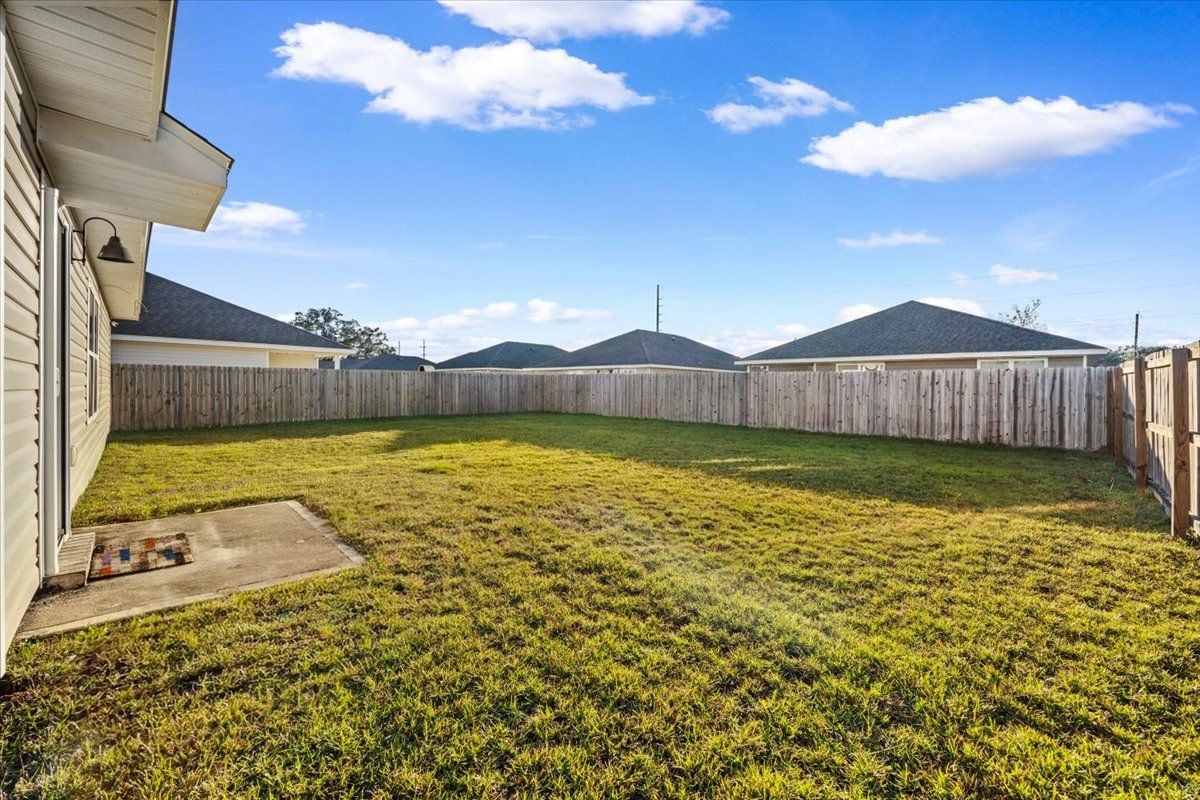
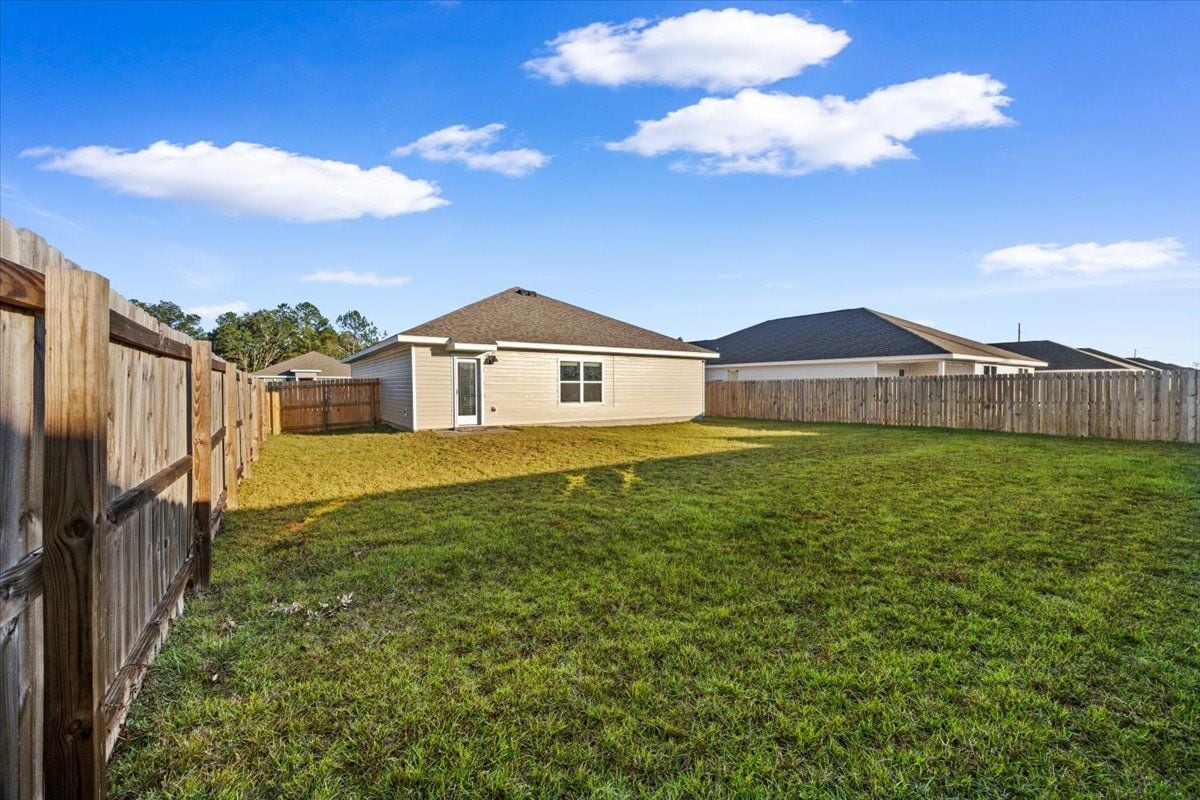
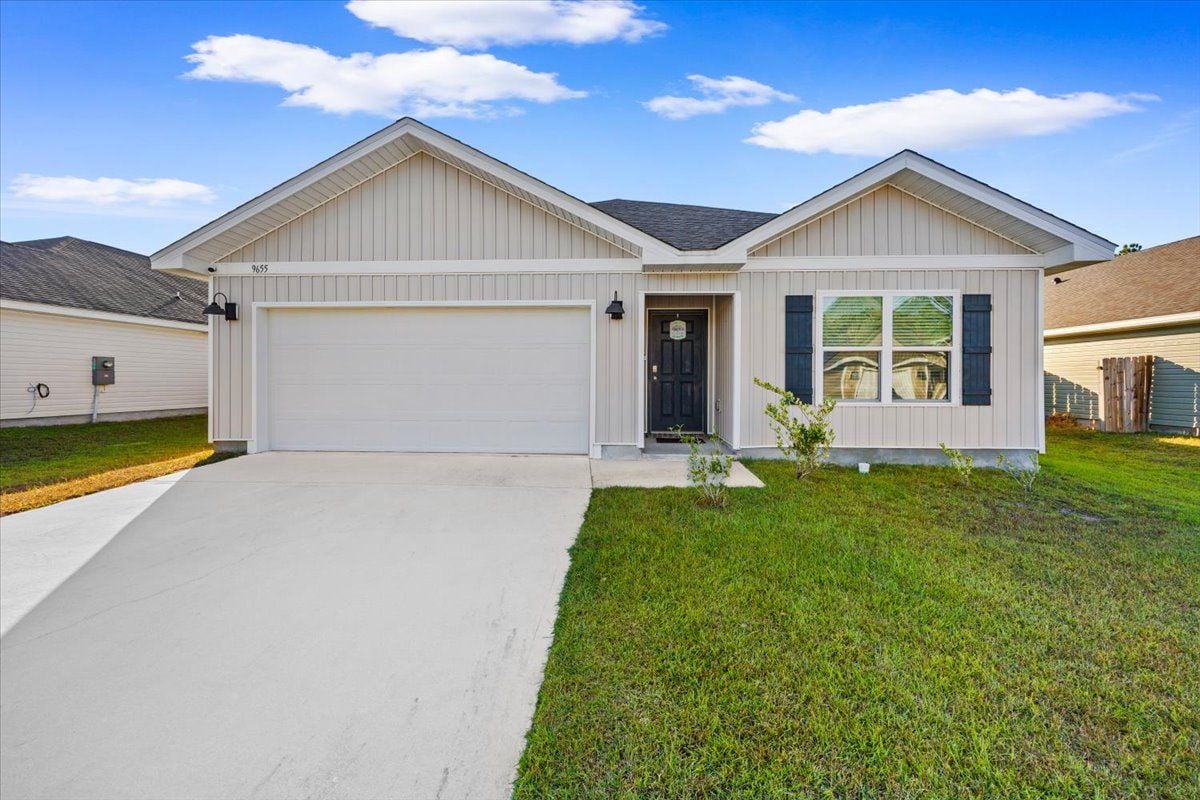
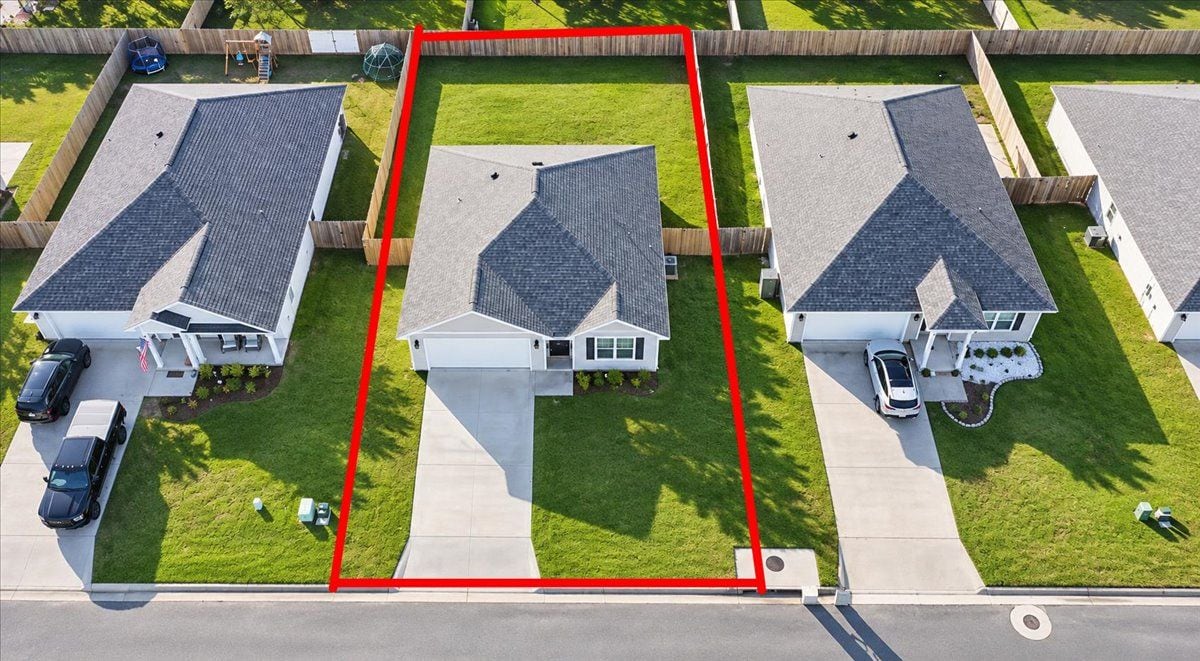
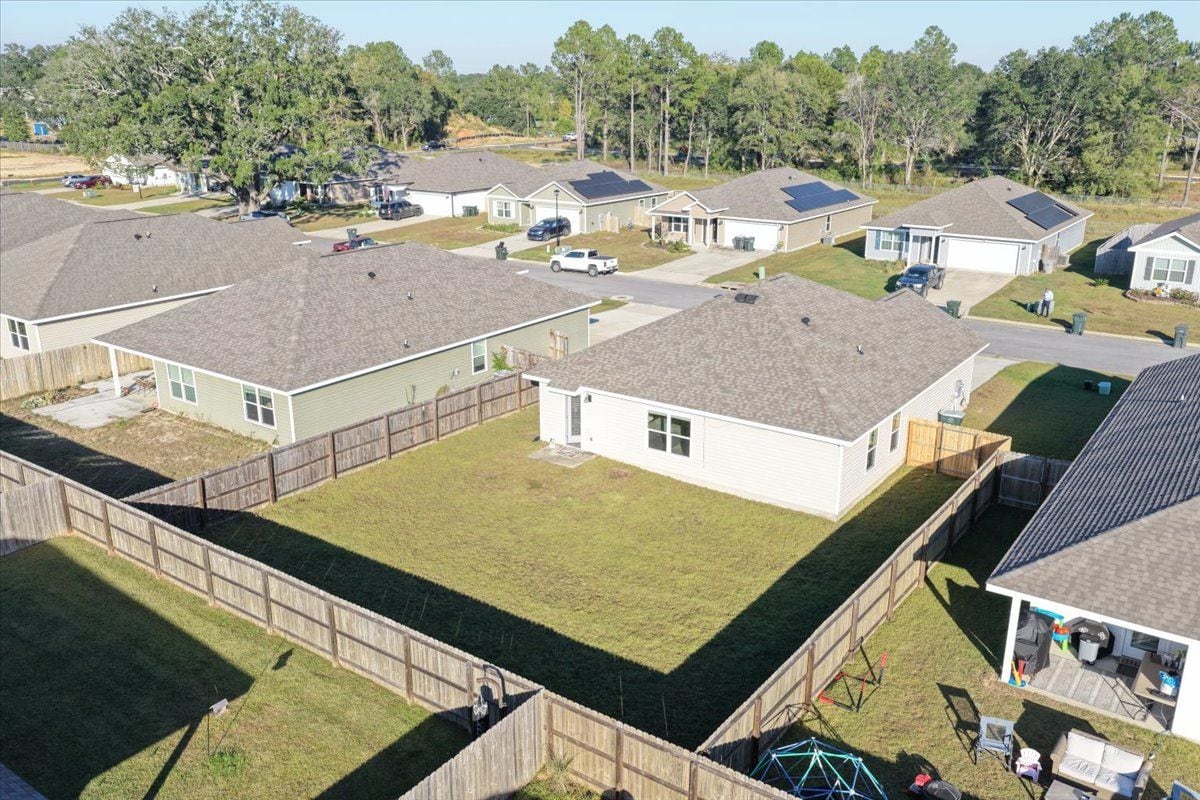
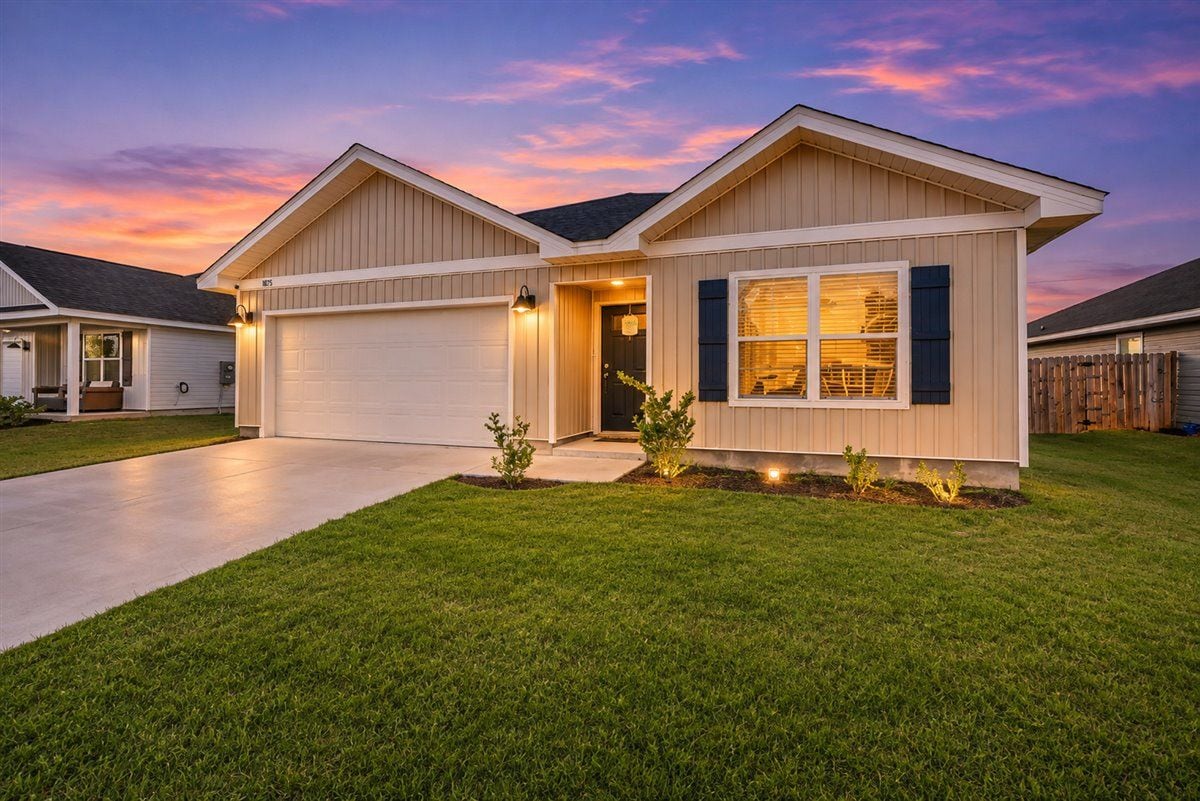
Photographs by the listing photographer, delivered in November 2026. Skies and lighting may be digitally enhanced, and the dusk exterior is a digital twilight edit. No room is virtually staged. Furnishings are not included in the sale unless the contract says so.
Walk through before you visit
A closer look at the rooms and the outdoor space at 9655 Angel Oak Drive.
Property video from the listing photographer, hosted on Vimeo. Furnishings and decor are not included in the sale unless the contract says so. If the player does not appear, open the video in a new tab .

A newer home in northwest Pensacola
Three bedrooms, an open plan and a fenced yard on one level, in a neighborhood of recently built homes.
What the home offers
Drawn from county records, the photographer's floor plan and the seller's disclosures. Appliances and other personal property convey only as written in the sales contract.
- Three bedrooms and two full baths on one level
- Split-bedroom floor plan
- Open kitchen, dining and living area
- Kitchen island with seating
- Walk-in closet in the primary suite
- Double vanity and walk-in shower in the primary bath
- Laundry closet off the hall
- Attached garage, 420 square feet per county records
- Covered front entry and a patio slab at the back door
- Backyard with privacy fencing
- Central heating and cooling
- Homeowners association, $450 a year per the seller's disclosure
The details behind the home
A starting point for your questions. Ask Gregg for the seller disclosures before you write an offer.
1 · HOA and ownership costs
Glenhollow has a mandatory homeowners association. The seller's HOA disclosure lists dues of $450 a year; confirm current dues, rules and any assessments with the association. The recorded plat shows privately maintained roads. Get your own insurance quotes and property tax estimate, because the current owner's tax bill reflects a homestead exemption.
2 · Wastewater and disclosures
The seller's disclosure reports a septic system, while an earlier MLS record for the home reported public sewer. Verify the service with the utility and have any septic system inspected. Ask for the completed flood disclosure and the full seller disclosure before you make an offer.
3 · Condition and measurements
The seller reports a four-year-old roof and working heating and cooling. These are the seller's statements, not inspection findings or warranties. County records show 1,270 square feet of living area; an earlier MLS record showed 1,272. Room sizes on the floor plan are approximate.
Read the complete buyer package
Four pages to keep or share: the home, the assumable loan and its numbers, ownership costs and the questions to ask. Reviewed November 17, 2026.
A clear look at the home and the loan
Gregg Costin is a Realtor with Dalton Wade in Pensacola, Florida, a retired U.S. Air Force Captain with 12 years in real estate and 11 personal PCS moves, licensed in Florida (SL3630964) and Alabama (000171694-0), specializing in military relocation and VA purchases and serving civilian buyers and sellers from Perdido Key to Destin and coastal Alabama.
On an assumption, Gregg asks the servicer for the exact figures early, builds its review time into the contract and keeps both sides informed until closing.
Glenhollow, Pensacola
9655 Angel Oak Drive, Pensacola, FL 32526. Glenhollow is in northwest Pensacola, in the Beulah school zone. In a straight line the home is about 5 miles from Saufley Field, 10 miles from Corry Station and 13 miles from NAS Pensacola.
School assignments come from the Escambia County school district's address lookup on November 13, 2026. Confirm them with the district before you rely on them.
Ask about 9655 Angel Oak Drive
Tell me a little about your plans and I will send the disclosures, walk you through the assumption or set up a showing.